
In the high-stakes corridors of Dhaka’s financial district, where balance sheets are scrutinized down to the decimal and macroeconomic headwinds test the mettle of every commercial lender, the transition from theoretical science to executive banking might seem like an unlikely trajectory. Yet, for Arif Hasan Khan, Deputy Managing Director (DMD) and Chief Risk Officer (CRO) at Modhumoti Bank PLC, the laws of physics and the mechanics of modern finance share a common foundation: equilibrium, precision, and the rigorous calculation of force and resistance.
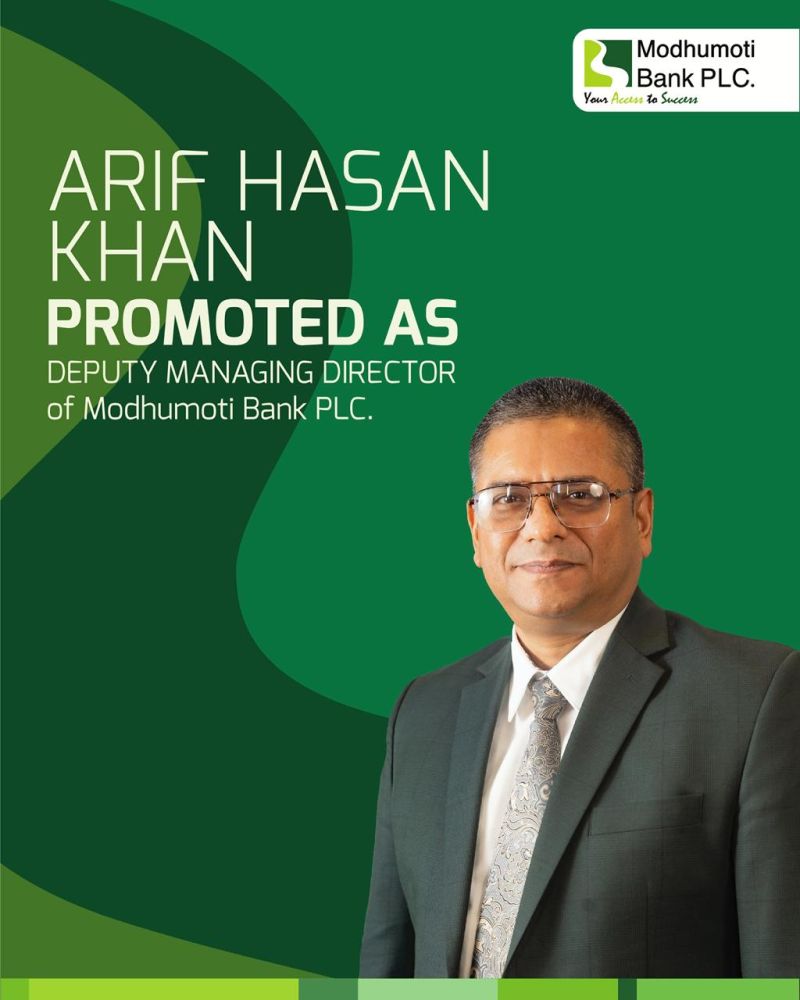
When Modhumoti Bank PLC elevated Khan to the rank of Deputy Managing Director on July 1, 2026, the announcement marked far more than a routine corporate promotion. It was the culmination of over twenty-four years of methodical career building across three prominent private commercial banks in Bangladesh. More importantly, it reflected a broader shift in the country’s banking sector—a deliberate pivot toward seasoned risk architects capable of steering institutions through complex credit environments, regulatory tightening, and the emerging demands of sustainable finance.
Today, as both DMD and CRO, Khan sits at the nerve center of Modhumoti Bank’s strategic decision-making. His journey from a physics lecture hall at the University of Dhaka to the upper echelons of corporate banking offers a compelling study in disciplined progression, technical mastery, and institutional stewardship.
The Analytical Foundation: From Dhaka University to Prime Bank
Before he was structuring multi-crore syndicated loans or stress-testing corporate credit portfolios, Arif Hasan Khan was immersed in the fundamental laws of the physical universe. He earned both his Bachelor of Science (BSc) and Master of Science (MSc) degrees in Physics from the University of Dhaka, the nation’s premier academic institution.
In South Asian corporate culture, science graduates entering the financial sector is a well-documented phenomenon, often driven by the quantitative rigor that disciplines like physics instill. Physics demands an ability to isolate variables, model complex systems, and predict outcomes under varying conditions—skills that translate seamlessly into financial modeling, credit risk assessment, and portfolio management. Recognizing the need to pair his analytical training with commercial acumen, Khan subsequently completed a Master of Business Administration (MBA) with a concentration in Marketing. This dual academic background gave him a rare hybrid profile: the quantitative discipline of a scientist combined with the client-centric, strategic mindset of a business strategist.
Khan’s formal entry into the banking industry began in 2001, a transformative period for Bangladesh’s private banking sector. Private commercial banks were rapidly modernizing, adopting core banking software, and expanding beyond traditional trade finance into large-scale industrial project financing. Khan joined Prime Bank PLC—widely regarded at the time as a breeding ground for top-tier banking talent—as a Probationary Officer.
The probationary officer track in Bangladeshi banking is famously demanding, designed to expose young recruits to the granular realities of branch operations, general banking, foreign exchange, and credit administration. Over a tenure spanning more than a decade at Prime Bank, Khan distinguished himself through his aptitude for complex deal-making. He steadily rose through the ranks to lead the bank’s Structured Finance and Syndication unit.
During the late 2000s and early 2010s, Bangladesh’s industrial landscape was expanding rapidly. Textile conglomerates, power generation companies, telecommunications operators, and heavy manufacturers required capital outlays that exceeded the single-borrower exposure limits of individual banks. Syndicated lending—where multiple banks pool resources under a lead arranger to finance a single large project—became the lifeblood of industrial growth. Leading Structured Finance and Syndication at Prime Bank placed Khan at the center of this ecosystem. Structuring these transactions required deep due diligence, cash-flow forecasting, legal coordination, and the ability to align diverse institutional lenders around a shared risk appetite. It was here that Khan honed his signature expertise in project finance and intricate credit structuring.
Scaling Corporate Operations at Bank Asia
After more than ten years at Prime Bank, Khan sought broader operational exposure in corporate asset management. He joined Bank Asia PLC, another leading private commercial lender, where he served as First Vice President and Unit Head of Corporate Assets.
At Bank Asia, Khan’s mandate expanded from specialized deal structuring to supervising corporate credit operations across multiple branches. Managing corporate assets across a distributed branch network presents distinct operational challenges. Unlike centralized syndication desks, branch-level corporate lending requires close coordination with relationship managers on the ground, continuous monitoring of working capital cycles, and strict adherence to credit compliance across diverse regional markets.
During his tenure at Bank Asia, Khan solidified his reputation as a banker who could balance business growth with asset quality. In an industry often torn between aggressive loan book expansion and conservative credit underwriting, he demonstrated that thorough upfront structuring was the most effective safeguard against future non-performing loans (NPLs).
A Decade of Institution-Building at Modhumoti Bank
In May 2014, Arif Hasan Khan made a pivotal career move, joining Modhumoti Bank PLC as a Vice President. At the time, Modhumoti Bank—which commenced operations in 2013 as one of Bangladesh’s fourth-generation private commercial banks—was still in its formative phase. Entering a young institution carried inherent challenges: establishing market credibility, building robust internal control frameworks from the ground up, and competing for prime corporate clients against established first- and second-generation banks.
For a seasoned corporate and structured finance specialist, however, a fourth-generation bank offered a blank canvas to build institutional architecture the right way. Over the next twelve years, Khan became one of the primary architects of Modhumoti Bank’s corporate credit and risk governance frameworks.
As he progressed from Vice President to Senior Executive Vice President (SEVP), Khan took on an increasingly comprehensive portfolio. Prior to his elevation to Deputy Managing Director, he oversaw three critical pillars of the bank’s operations: Corporate and Investment Banking, Risk Management, and Corporate Credit.
Holding concurrent oversight over both business generation (Corporate and Investment Banking) and control functions (Risk Management and Corporate Credit) required a delicate institutional balance. Throughout his tenure, Khan focused on several foundational areas:
- Strengthening Credit Structuring: Drawing on his syndication and project finance background, he helped formalize rigorous underwriting standards, ensuring that corporate facilities were aligned with borrowers’ actual cash-conversion cycles rather than relying solely on collateral coverage.
- Elevating Risk Governance: As regulatory frameworks evolved under Bangladesh Bank’s guidelines—including the implementation of Basel III capital standards and Enterprise Risk Management (ERM) protocols—Khan played a central role in embedding risk awareness into the bank’s operational DNA.
- Advancing Sustainable Banking: Recognizing the global and domestic shift toward environmental, social, and governance (ESG) criteria, he championed sustainable banking practices, integrating environmental and social risk management (ESRM) into credit evaluation processes.
His contributions did not go unnoticed within the institution or the wider industry. Alongside his technical certifications—including Omega Performance certification in relationship banking, loan structuring, credit policy formulation, and risk management, as well as specialized training in trade finance, Basel II/III, and financial modeling—Khan was also recognized as an Integrity Award Certificate winner, an accolade reflecting ethical conduct and governance compliance in an industry where trust is paramount.
The Dual Mandate: Deputy Managing Director and Chief Risk Officer
When the Board of Directors of Modhumoti Bank PLC promoted Arif Hasan Khan to Deputy Managing Director effective July 1, 2026, while retaining him as Chief Risk Officer, the decision underscored a critical reality of contemporary banking leadership.
Historically, the Chief Risk Officer in many South Asian banks was viewed primarily as a compliance gatekeeper—a defensive role focused on saying “no” to overly aggressive relationship managers. In modern banking, however, the CRO is a strategic co-pilot. Particularly in Bangladesh’s banking sector, which has spent the mid-2020s navigating inflationary pressures, foreign exchange volatility, interest rate adjustments, and heightened regulatory scrutiny over asset quality, risk management is indistinguishable from core corporate strategy.
As DMD and CRO, Khan occupies a unique vantage point. He participates directly in the bank’s Management Committee, shaping high-level strategic priorities alongside the Managing Director and fellow DMDs, while simultaneously safeguarding the institution’s balance sheet.
In this dual capacity, his strategic priorities center on three interconnected imperatives:
- Proactive Portfolio Resilience: Rather than reacting to credit deterioration after a borrower defaults, modern risk leadership relies on early warning signals, sector-specific stress testing, and dynamic exposure limits. Khan’s background in financial modeling and structured finance equips him to dissect sector-level vulnerabilities—whether in readymade garments, steel, pharmaceuticals, or infrastructure—before they manifest as stressed assets.
- Harmonizing Growth with Compliance: Every commercial bank must generate returns for its shareholders by deploying capital profitably. Khan’s experience leading corporate banking units allows him to understand the commercial realities faced by relationship managers and corporate clients. Instead of creating bureaucratic bottlenecks, effective risk governance under his purview aims to structure deals intelligently so that viable businesses receive timely financing under well-mitigated terms.
- Institutionalizing a Risk-Aware Culture: Policies and manuals alone cannot protect a bank; risk management must be practiced at every branch counter and credit desk. Through continuous process improvement and internal capacity building—including regularly engaging with Modhumoti Bank’s learning and development initiatives—Khan has emphasized human capital development as the first line of defense against operational and credit risk.
- Leadership Philosophy and Engagement Beyond the Desk
- Colleagues and industry observers often characterize Khan’s leadership style as methodical, collaborative, and deeply grounded in technical competence. Having climbed the ladder from an entry-level Probationary Officer in 2001 to the C-suite in 2026, he possesses an intimate familiarity with every operational layer of a commercial bank.
- Beyond his day-to-day executive duties, Khan remains actively engaged in knowledge sharing and academic-industry bridging. Whether participating in internal training workshops on specialized products like work-order financing at the Modhumoti Learning and Development Center or addressing incoming Executive MBA cohorts at public universities such as Comilla University, he consistently advocates for continuous learning and ethical professionalism among emerging business leaders.
- His message to young bankers and business students frequently returns to fundamentals: master the technical craft, understand the underlying economics of the businesses you finance, and never compromise on institutional integrity.
- Looking Ahead: Steering Through a Transforming Financial Landscape
- As Bangladesh’s economy progresses toward upper-middle-income aspirations and prepares for the structural shifts accompanying graduation from Least Developed Country (LDC) status, its banking sector faces a defining decade. Domestic industries will require sophisticated project financing, green transition capital, and resilient supply-chain liquidity. Simultaneously, banks will be held to stricter international standards of governance, capital adequacy, and transparency.
- For Modhumoti Bank PLC, having a leader of Arif Hasan Khan’s caliber at the helm of risk and executive management provides vital institutional stability. Over twenty-four years after leaving the physics laboratories of Dhaka University to enter a bank branch as a trainee, Khan has proven that the most durable financial institutions are built much like sound physical structures—through careful calculation, balanced forces, and an unwavering respect for foundational principles.